
Most people don’t overspend because they’re careless. They overspend because money has become invisible. You tap a card, scan a phone, click “buy now,” and the cost barely registers until the statement arrives. By then, it’s too late to do anything about it.
Envelope budgeting fixes that problem in one of the oldest ways possible: you put physical cash into labeled envelopes, and when an envelope is empty, that category is done for the month.
It sounds almost too simple to work. Yet this method has helped families, students, freelancers, and first-time budgeters get control of their spending for generations. In this guide, you’ll learn exactly how the cash envelope system works, how to set it up step by step, what to do when things go wrong, and how to adapt it to a world where so much of our money is digital.
What Is Envelope Budgeting?
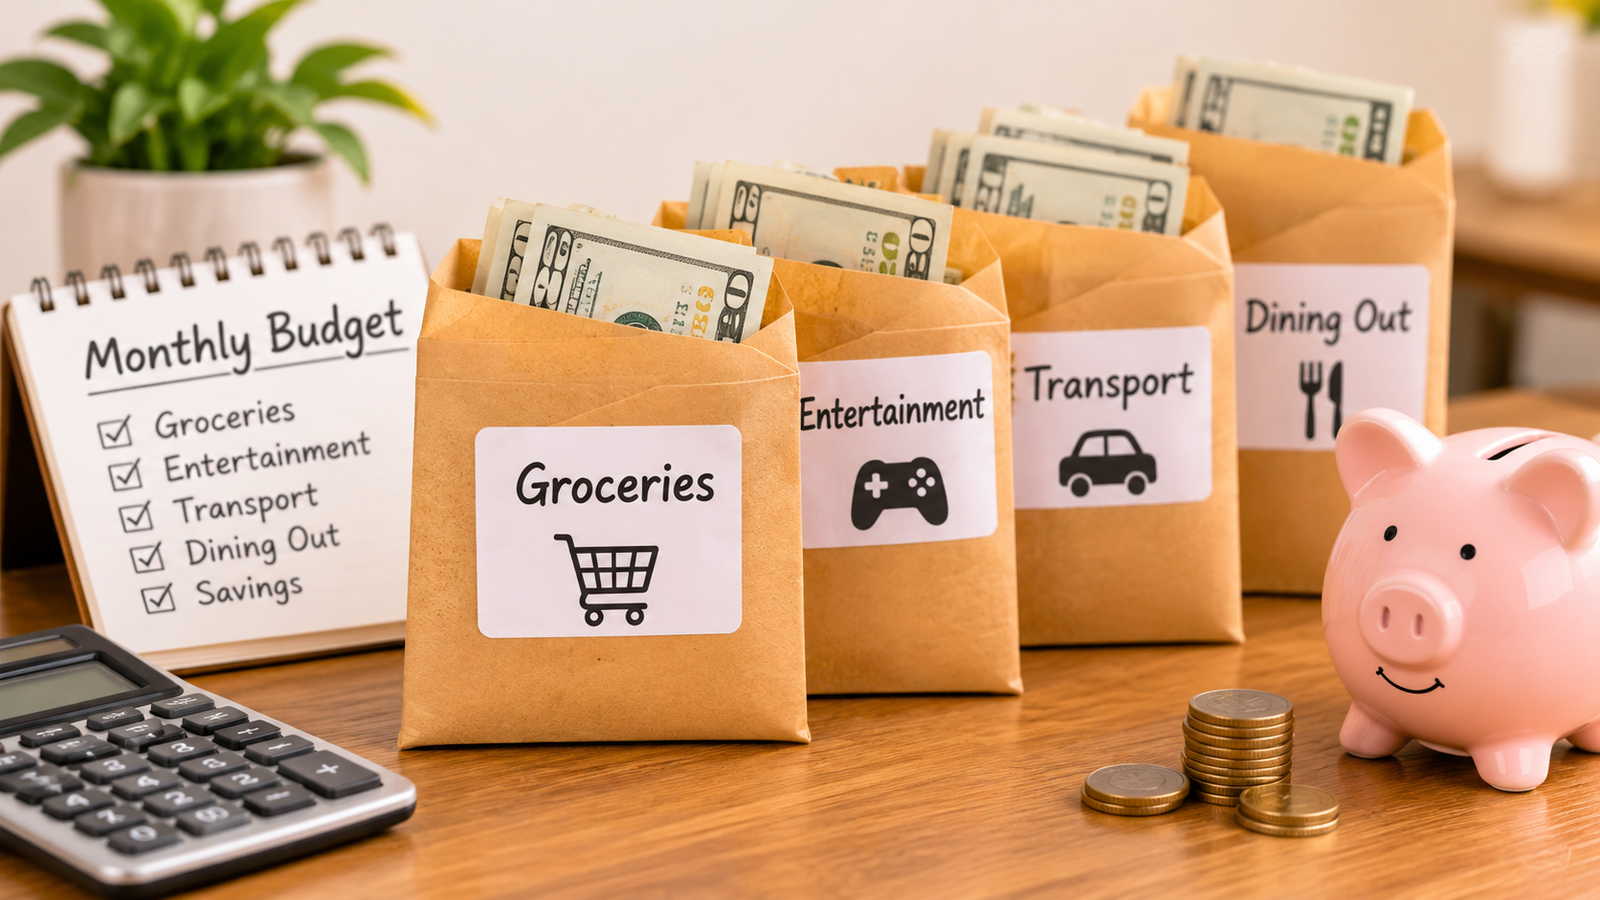
Envelope budgeting, also called the cash envelope system, is a budgeting method where you divide your spending money into categories and assign a physical envelope to each one. Groceries get an envelope. Transport gets an envelope. Eating out, entertainment, and personal spending each get their own.
At the start of the month (or each pay period), you withdraw the cash you plan to spend and distribute it among the envelopes. Whenever you spend in a category, you pay from that envelope. When the money runs out, you stop spending in that category until the next cycle.
That’s the whole system. The power is in its simplicity: your budget stops being a number on a spreadsheet and becomes something you can see and hold.
Why the Cash Envelope System Works
The method works because of how our brains treat money. Research in behavioral finance has repeatedly shown that people feel the “pain of paying” more when they hand over physical cash than when they swipe a card. Spending cash feels like losing something real, so you naturally think twice.
Here are the main reasons envelope budgeting is effective:
It creates a hard spending limit. A budget on paper is a suggestion. An empty envelope is a boundary. You can’t overspend what you don’t have in your hand.
It makes tradeoffs visible. If your entertainment envelope has $20 left and there are two weeks to go, you have to decide what matters. That kind of decision-making builds financial awareness.
It’s easy to understand. You don’t need budgeting software, financial vocabulary, or a spreadsheet. Anyone in the household, including teenagers, can follow it.
It reduces impulse buying. When you have to open an envelope and count out bills, the quick, thoughtless purchase becomes a little harder to justify.
What You’ll Need to Get Started
You don’t need much:
- A set of envelopes (plain paper envelopes work fine, or buy a dedicated cash envelope wallet)
- A pen or marker for labeling
- Your monthly income and a list of expenses
- Cash withdrawn from your bank account
- A safe place to keep your envelopes
How to Set Up Envelope Budgeting: Step by Step
Step 1: Calculate Your Monthly Income
Start with how much money you actually take home each month, after taxes and deductions. If your income is irregular, as it is for many freelancers and business owners, use your lowest-earning month from the past six months as your baseline. This keeps the budget realistic.
Step 2: List Your Expenses and Sort Them
Write down everything you spend money on. Then split the list into two groups:
Fixed expenses stay the same every month, like rent, loan payments, insurance, and subscriptions. These are usually paid by bank transfer or direct debit, so they don’t need envelopes.
Variable expenses change from month to month, like groceries, fuel, dining out, clothing, entertainment, and personal care. These are the categories that belong in your envelopes, because they’re where most overspending happens.
Step 3: Choose Your Envelope Categories
Pick the variable categories where you most need control. Common choices include:
- Groceries
- Transport or fuel
- Eating out
- Entertainment
- Clothing and shopping
- Personal care
- Household supplies
- Miscellaneous or “fun money”
Start with five to eight envelopes. Too many becomes tedious, and too few doesn’t give you enough control.
Step 4: Set a Budget for Each Envelope
Look at your past two or three months of spending to estimate realistic amounts. If you’ve been spending $400 a month on groceries, don’t suddenly assign $150 and expect it to work. Start with honest numbers, then trim gradually.
Make sure your total envelope amounts, plus your fixed expenses and savings, don’t exceed your income. If they do, you’ll need to reduce something.
Step 5: Withdraw the Cash and Fill the Envelopes
Take out the total amount you need from your bank account, ideally in smaller denominations so it’s easier to divide. Write the category and amount on each envelope, then place the cash inside.
Step 6: Spend Only From the Envelope
When you shop, take only the relevant envelope with you. Going to the grocery store? Take the grocery envelope and leave the rest at home. This habit alone prevents a lot of accidental overspending.
Step 7: Track and Adjust
Keep the receipts, or jot down what you spent inside each envelope. At the end of the month, review what happened. Which envelopes ran out early? Which had money left over? Use that information to adjust the amounts for next month.
A Simple Example
Say you earn $2,000 a month after tax. Your rent, utilities, and phone bill come to $1,100, and you want to save $200. That leaves $700 for variable spending, which you divide like this:
| Envelope | Monthly Amount |
|---|---|
| Groceries | $300 |
| Transport | $120 |
| Eating out | $80 |
| Entertainment | $60 |
| Personal care | $40 |
| Miscellaneous | $100 |
| Total | $700 |
Your fixed bills and savings are handled by bank transfer, and the $700 sits in your envelopes. If the eating-out envelope is empty by the 20th, you cook at home until payday. No guilt, no debt, no surprise.
What Happens When an Envelope Runs Out?
This is the question every beginner asks, and it’s where the system earns its value. You have a few options:
Stop spending in that category. This is the purest version of the method, and it teaches discipline fast.
Borrow from another envelope. If you must, move money from a category with a surplus, such as entertainment, to cover a real need. Treat this as an exception, not a habit.
Adjust next month’s budget. If you consistently run out of money in one envelope, your original estimate was too low. Increase it and lower something else.
The point isn’t punishment. It’s information. An empty envelope tells you something real about your spending.
What to Do With Leftover Money
Money left in an envelope at month’s end is a win. You can handle it in one of three ways:
- Roll it over to the same envelope for next month
- Move it into your savings or emergency fund
- Put it toward debt repayment
Many people find that moving leftovers into savings is the most motivating choice, since it turns good spending habits into visible progress.
Pros and Cons of the Cash Envelope System
Advantages
- Easy to set up and easy to understand
- Builds awareness of where your money goes
- Naturally limits overspending
- Works without technology or fees
- Helps people get out of credit card debt
Disadvantages
- Carrying cash carries a risk of loss or theft
- Many bills and online purchases can’t be paid in cash
- It requires a trip to the bank or ATM
- Tracking can feel inconvenient compared to automated apps
- You may miss out on card rewards or cashback
None of these are dealbreakers, but they’re worth knowing about before you start.
Can You Do Envelope Budgeting Digitally?
Yes. Because cash isn’t practical for everyone, digital versions have become popular. Budgeting apps let you create “virtual envelopes” and assign money to each category, so you can see your remaining balance as you spend with a card. Some banks also let you create separate sub-accounts or “pots” for different spending goals.
Digital envelopes give you the same structure with more convenience and better record-keeping. The tradeoff is that they lose some of the psychological bite of handing over real bills. A good approach is a hybrid: use physical cash for the categories where you struggle most, such as eating out and shopping, and digital envelopes for everything else.
Tips for Making Envelope Budgeting Work
Be realistic from the start. An overly strict budget will fail by week two. Give yourself some breathing room.
Include a “fun money” envelope. Budgets that leave no room for enjoyment don’t last. A small amount for guilt-free spending keeps you motivated.
Keep your envelopes secure. Don’t carry more cash than you need, and store the rest somewhere safe at home.
Involve your household. If you share finances with a partner or family, agree on the categories and amounts together so everyone follows the same plan.
Review monthly. Your life changes, and your budget should change with it.
Start small. If a full system feels like too much, begin with just the one or two categories where you overspend most.
Common Mistakes to Avoid
The biggest mistake is making the budget too tight, then giving up when it fails. Another is forgetting irregular expenses, such as car repairs, gifts, or school fees. Consider creating a small “sinking fund” envelope for these so they don’t wreck your month.
Also avoid dipping into your savings envelope for non-emergencies, and don’t treat the system as a punishment. It’s a tool to give you control, not a test you can fail.
Is Envelope Budgeting Right for You?
The cash envelope system is especially useful if you tend to overspend on cards, you’re paying off debt, you’re new to budgeting, or you simply want a clear picture of your spending. It may be less suitable if most of your spending happens online or if carrying cash isn’t safe where you live. In that case, the digital approach is the better fit.
Final Thoughts
Envelope budgeting has lasted for decades for a simple reason: it works with human psychology instead of against it. When your money is limited to what’s in front of you, you make better choices without needing willpower or complicated tools.
You don’t have to be perfect. Start with a few categories, fill your envelopes this month, and see what you learn. Within a few weeks, you’ll likely notice that you’re spending more intentionally and worrying less about money.
Ready to try it? Grab a few envelopes, work out your numbers, and give the cash envelope system one full month. Your future self will thank you.