Category: Investing & Wealth Building

  • Risk Tolerance: The 7 Ultimate Guide to Your Investing Comfort Zone

    Risk Tolerance: The 7 Ultimate Guide to Your Investing Comfort Zone

    Imagine you’ve invested $10,000, and one morning Risk Tolerance you open your app to find it’s now worth $8,000. What do you do? Sell everything and stop the pain? Hold steady and wait? Or buy more while prices are low?

    Your honest answer to that question says a lot about your risk tolerance. And it may be the most important thing to understand before you invest a single dollar.

    Many beginners focus on picking the “best” investment. But the best investment on paper is useless if it scares you into selling at the worst moment. This guide explains what risk tolerance is, what shapes it, how to measure it, and how to build a portfolio that fits you, so you can invest with confidence instead of anxiety.

    What Is Risk Tolerance?

    Risk tolerance is the amount of investment loss, or ups and downs in value, that you can handle both financially and emotionally without abandoning your plan.

    Put simply, it answers the question: how much volatility can you live with while still sleeping well at night?

    Investing always involves a trade-off. Higher potential returns usually come with bigger swings and a greater chance of loss. Lower-risk options such as savings accounts and government bonds are steadier but tend to grow more slowly. Your risk tolerance helps you decide where on that spectrum you belong.

    Risk Tolerance vs Risk Capacity vs Risk Required

    These three terms are often confused, but understanding all of them leads to better decisions.

    Risk tolerance is your emotional comfort with losses. It’s about psychology.

    Risk capacity is your financial ability to absorb losses. A person with a stable income, low debt, and a big emergency fund has a higher capacity than someone living paycheck to paycheck.

    Risk required is the level of risk you need to take to reach your goal. If you want to turn a small sum into a large one in a short time, the required risk is high, and often unrealistic.

    The healthiest investing plan balances all three. You might feel brave (high tolerance) but have little financial cushion (low capacity). In that case, the sensible move is to invest more cautiously until your finances are stronger.

    Why Knowing Your Risk Tolerance Matters

    Investors tend to make their biggest mistakes when emotions take over. Fear during a crash leads people to sell low, and excitement during a boom leads them to buy high.

    Knowing your risk tolerance helps you:

    Avoid panic selling. If your portfolio matches your comfort level, a downturn feels uncomfortable but manageable.

    Stay invested long term. Time in the market is what builds wealth, and you can’t benefit if you keep dropping out.

    Choose suitable investments. You’ll avoid products that are too aggressive or too timid for your situation.

    Reduce regret. Decisions made with self-awareness are easier to live with.

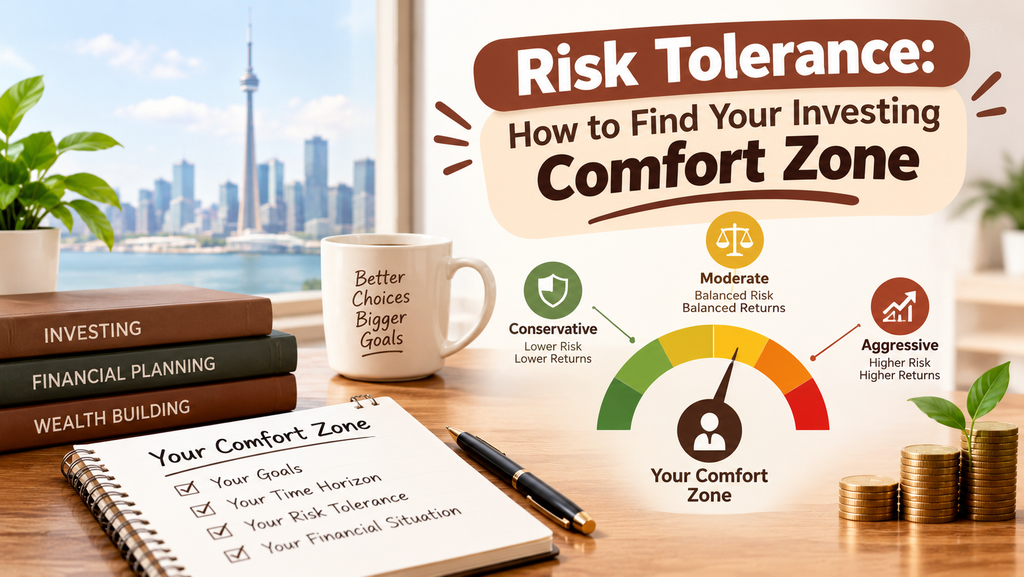
    The 3 Main Types of Risk Tolerance

    Most investors fall into one of three broad groups.

    Conservative

    Conservative investors prioritize protecting their money over growing it quickly. They’re uneasy with large swings and prefer stability. Their portfolios usually lean toward savings, bonds, and other lower-volatility assets, accepting slower growth in exchange for peace of mind.

    Moderate

    Moderate investors want growth but dislike extreme volatility. They typically hold a balanced mix of stocks and bonds. They can tolerate some losses in bad years because they expect better returns over time.

    Aggressive

    Aggressive investors chase higher long-term growth and can handle sharp drops without losing their nerve. Their portfolios are stock-heavy and may include higher-risk assets. They accept that big gains and big losses can both happen.

    None of these is better than another. The right one is the one you can actually stick with.

    What Influences Your Risk Tolerance?

    Your comfort with risk isn’t random. Several factors shape it.

    Age and time horizon. The longer you have until you need the money, the more time you have to recover from downturns. A 25-year-old saving for retirement can generally take more risk than a 60-year-old who retires soon.

    Financial goals. Money for a house deposit in two years needs more protection than money for retirement in thirty.

    Income stability. A steady salary makes losses easier to absorb than irregular earnings.

    Savings and debts. A strong emergency fund and low debt give you more room to take investment risk.

    Experience. People who have lived through market ups and downs often become more comfortable with volatility, while beginners may feel shaken by their first dip.

    Personality. Some people are naturally cautious, others naturally adventurous. This is a legitimate factor, so be honest about yours.

    7 Powerful Steps to Find Your Investing Comfort Zone

    Step 1: Define Your Goals and Timelines

    Start by listing what you’re investing for and when you’ll need the money. Short-term goals (under three to five years) call for safer assets. Long-term goals allow more risk.

    Step 2: Check Your Financial Foundation

    Before investing, make sure you have an emergency fund covering several months of expenses and a plan for any high-interest debt. Without that foundation, even a small market dip can force you to sell. [INTERNAL LINK: add a link here to your Growwxritik post on building an emergency fund]

    Step 3: Ask Yourself the Hard Questions

    Answer these honestly:

    • If my portfolio fell 20% in a few months, would I sell, hold, or buy more?
    • Could I leave this money alone for at least five years?
    • Would a large loss affect my ability to pay bills?
    • Do I check my investments obsessively and feel anxious when they fall?

    Your answers reveal more than any quiz.

    Step 4: Take a Risk Tolerance Questionnaire

    Many brokers and financial websites offer free risk questionnaires. They ask about your goals, timeline, and reactions to hypothetical losses, then suggest a profile such as conservative, moderate, or aggressive. Treat the result as a starting point, not a verdict. The Investor.gov guide to asset allocation explains how risk and return are connected and how this feeds into your mix of investments.

    Step 5: Look at Your Past Behavior

    How did you react during previous periods of uncertainty, such as a market crash, a job loss, or a major financial scare? Past behavior is often a better predictor than what you say you’d do. Many people believe they’re aggressive until they watch real money disappear.

    Step 6: Match Your Portfolio to Your Profile

    Once you know your comfort zone, build an asset allocation to match it. Conservative investors might hold more bonds and cash, moderate investors a balanced mix, and aggressive investors mostly stocks. Spreading your money across different assets also helps cushion shocks, as explained in [INTERNAL LINK: add a link here to your Growwxritik post on diversification]. For further reading, Investopedia’s explanation of risk tolerance offers helpful definitions.

    Step 7: Review and Adjust Over Time

    Your risk tolerance isn’t permanent. Marriage, children, a new job, a health scare, or approaching retirement can all change it. Revisit your plan at least once a year and after any major life event.

    Understanding the Risk and Return Trade-Off

    To see why this matters, imagine three simplified portfolios:

    Portfolio TypeTypical MixPotential ReturnTypical Swings
    ConservativeMostly bonds and cashLowerSmall
    ModerateBalanced stocks and bondsMediumModerate
    AggressiveMostly stocksHigherLarge

    These are general illustrations, not predictions. Actual results vary widely, and no investment is guaranteed. The key idea is that more potential growth usually means a bumpier ride.

    How to Stay Calm When Markets Fall

    Even with the right portfolio, downturns test your nerves. These habits help:

    Have a written plan. Decide in advance what you’ll do during a drop. A plan you wrote while calm is more reliable than a decision made in panic.

    Avoid constant checking. Looking at your portfolio daily magnifies anxiety. Check monthly or quarterly instead.

    Invest regularly. Putting in a fixed amount each month, known as dollar-cost averaging, reduces the pressure of timing the market.

    Remember history. Markets have fallen many times and have historically recovered over long periods, although there’s no guarantee of the future.

    Keep cash for emergencies. This prevents you from selling investments at a loss to pay urgent bills.

    Common Mistakes to Avoid

    Overestimating your courage. It’s easy to feel brave in a rising market. Be realistic about how you’d feel during a real loss.

    Underestimating your needs. Being too cautious can mean your money doesn’t keep pace with inflation, especially over long periods.

    Copying someone else’s portfolio. A friend’s aggressive strategy may not suit your goals, timeline, or nerves.

    Chasing hot trends. Buying into whatever is popular usually means taking risks you haven’t thought through.

    Never reviewing your plan. Life changes, and your portfolio should change with it.

    Investing money you’ll need soon. Short-term needs don’t belong in volatile assets.

    Frequently Asked Questions

    What is risk tolerance in investing?
    Risk tolerance is how much loss or volatility in your investments you can handle emotionally and financially without abandoning your plan.

    How do I find out my risk tolerance?
    Reflect on your goals and timeline, answer honest questions about how you’d react to losses, take a free questionnaire, and consider how you’ve behaved during past market scares.

    Does risk tolerance change with age?
    Often, yes. Younger investors typically have longer time horizons and can take more risk, while those near retirement usually shift toward stability. Personal circumstances and personality matter as well.

    What is a good risk tolerance for a beginner?
    There’s no universal answer, but many beginners start with a moderate approach, then adjust as they gain experience and confidence.

    Can I have a high risk tolerance but low risk capacity?
    Yes. You may feel comfortable with big swings but lack the financial cushion to survive a loss. In that case, it’s wise to invest more cautiously until your finances are stronger.

    Is low risk tolerance a bad thing?
    Not at all. It simply means you value stability. You can still build wealth steadily with a suitable portfolio and consistent saving.

    Final Thoughts

    Finding your risk tolerance isn’t about proving how brave you are. It’s about being honest with yourself, so you can build a plan you’ll actually follow when markets get rough. The best portfolio is not the one with the highest possible return. It’s the one that lets you stay invested, sleep well, and keep moving toward your goals.

    Start by defining your goals, check your financial foundation, answer the hard questions, and choose a mix that fits. Then review it regularly. Over time, understanding your risk tolerance will make you a calmer, more confident investor.
    This article is for educational purposes only and isn’t financial advice. All investing involves risk, including the possible loss of money. Consider consulting a licensed financial professional about your own situation.
  • What Is Diversification and Why Does It Matter?

    What Is Diversification and Why Does It Matter?


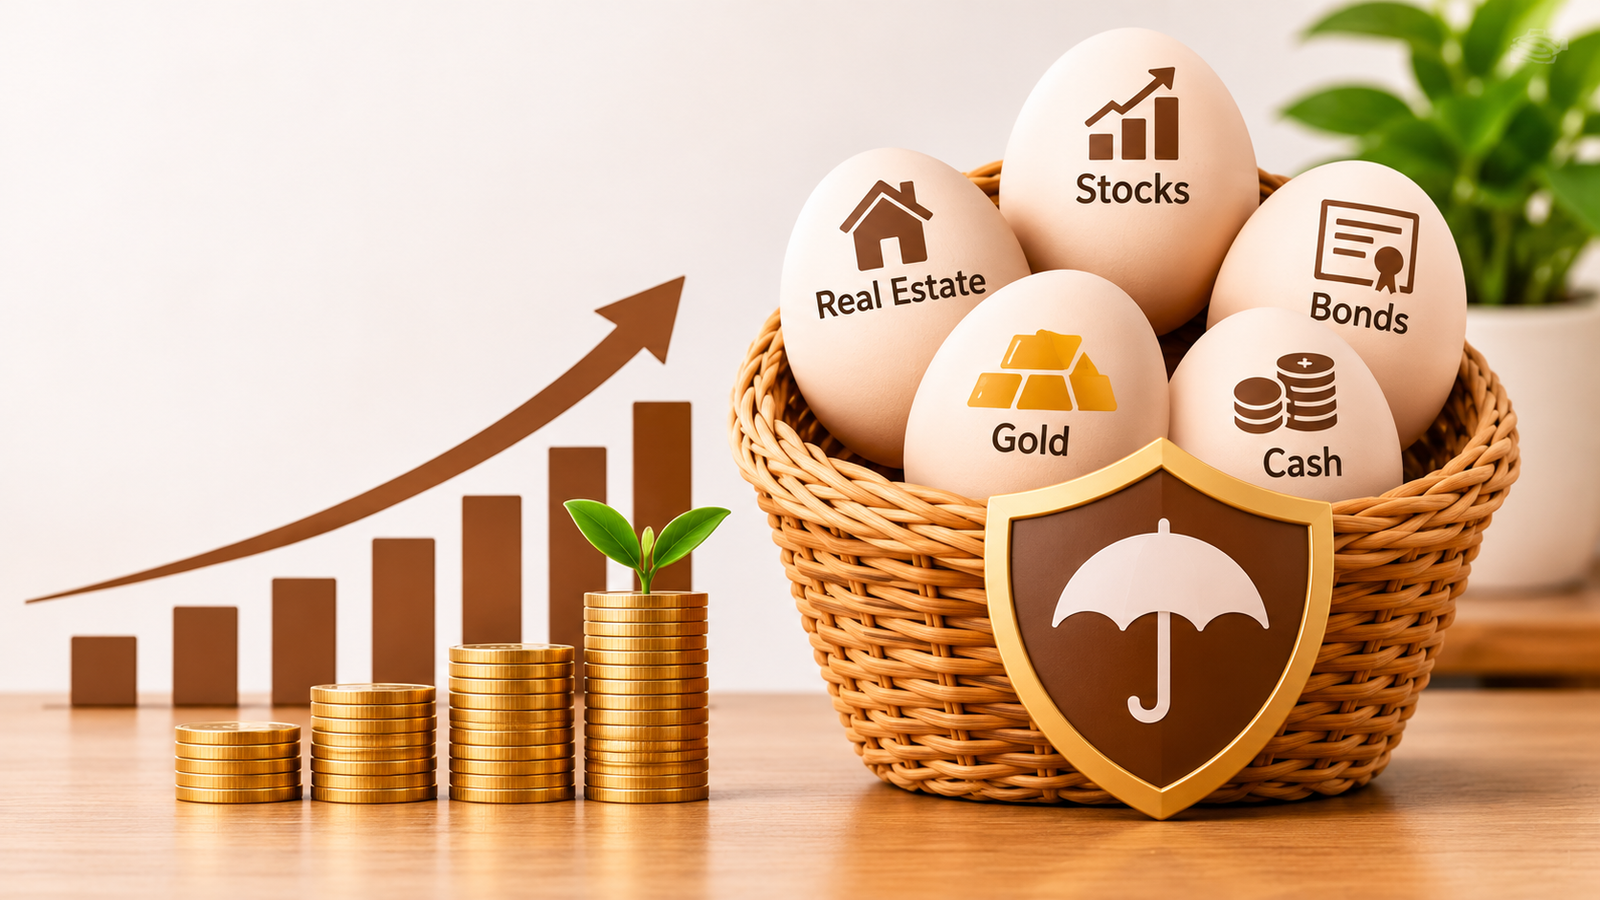
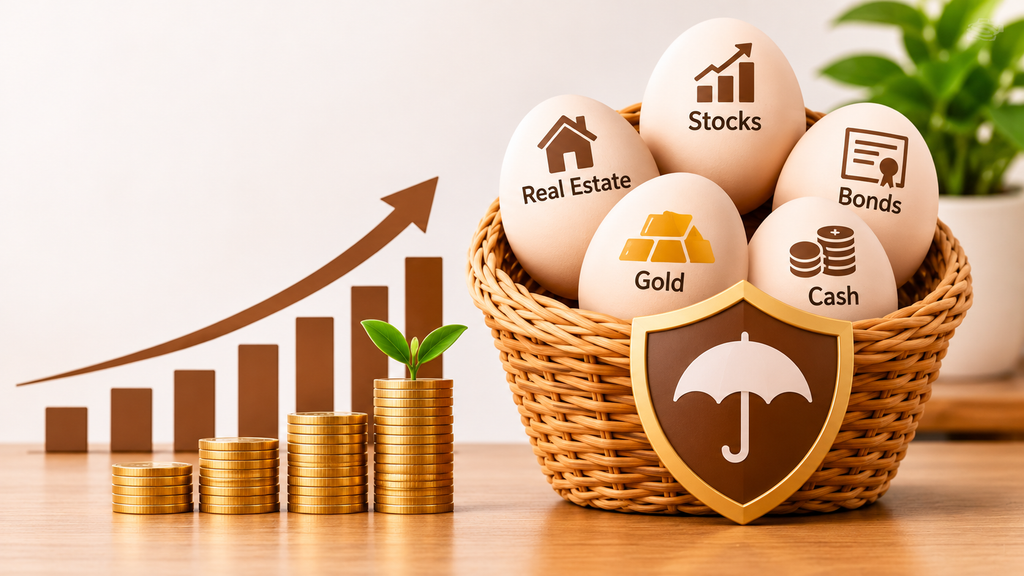
    Diversification is one of the most repeated ideas in investing, and one of the most misunderstood. You’ve probably heard the old advice, “don’t put all your eggs in one basket,” but what does that mean when you’re deciding where to put your money?

    In simple terms, diversification means spreading your investments across different assets so that no single bad outcome can wreck your finances. It won’t make you rich overnight, and it won’t remove risk completely. What it does is make your journey smoother and your losses easier to survive.

    This guide explains what diversification is, why it matters, how it works in practice, and how you can apply it with any budget, even if you’re just starting out.

    What Is Diversification?

    Diversification is an investment strategy where you divide your money among different types of investments, industries, and regions. The goal is to reduce the impact any single investment can have on your overall results.

    Think of two farmers. One grows only tomatoes. The other grows tomatoes, maize, beans, and peppers. If a disease wipes out the tomato crop, the first farmer loses everything for the season. The second farmer takes a hit but still has three other crops to sell.

    Your investments work the same way. When one holding drops, others may hold steady or even rise, which cushions the blow. That is the core idea behind diversification.

    Why Does Diversification Matter?

    Diversification matters because nobody can predict which investment will perform best next year. Even professional fund managers get it wrong regularly. The company that looks unstoppable today can collapse, and the sector everyone ignores can quietly deliver strong returns.

    Here are the main reasons diversification deserves a place in every financial plan:

    It reduces risk. Spreading your money limits how much any single failure can cost you.

    It smooths out returns. Because different assets rise and fall at different times, your overall portfolio tends to swing less dramatically.

    It protects you from your own mistakes. Everyone picks a bad investment eventually. Diversification keeps one mistake from becoming a disaster.

    It helps you stay calm. Investors who aren’t watching one holding nervously are less likely to panic and sell at the worst moment.

    It keeps you exposed to opportunity. You don’t have to guess the next winner. By owning a mix, you’re likely to hold at least some of the investments that do well.

    How Diversification Works: A Simple Example

    Imagine two investors who each have $10,000.

    Investor A puts everything into one company’s stock. Then the company runs into trouble and the share price falls 50%. Investor A’s money is now worth $5,000.

    Investor B splits the same $10,000 equally across ten different investments, $1,000 each. If one of them falls 50%, Investor B loses $500. If the other nine stay flat, the portfolio is worth $9,500, a loss of just 5%.

    Same starting amount, same bad event, completely different outcomes. That gap is the practical value of diversification. The more your holdings differ from one another, the more protection you get.

    The Main Types of Diversification

    Diversification isn’t just about owning many things. It’s about owning different things. Here are the main ways to do it.

    Diversification Across Asset Classes

    An asset class is a broad category of investment. The most common are:

    • Stocks (equities): ownership in companies, with higher growth potential and higher volatility
    • Bonds (fixed income): loans to governments or companies that pay interest, generally steadier than stocks
    • Cash and cash equivalents: savings accounts and money market funds, very stable but low-growth
    • Real estate: property or property-based funds
    • Commodities: gold, oil, and agricultural products

    Because these categories react differently to economic conditions, mixing them is the foundation of a diversified portfolio.

    Diversification Within an Asset Class

    Even inside stocks, you can spread risk. Own companies of different sizes (large, mid, and small), in different industries such as technology, healthcare, energy, and consumer goods. A portfolio made up of ten technology stocks may look diversified, but it’s really one big bet on a single sector.

    Geographic Diversification

    Economies don’t move in lockstep. When one country struggles, another may thrive. Investing across multiple regions, including developed and emerging markets, reduces your dependence on any one country’s economy, political situation, or currency.

    Diversification Over Time

    You can also spread risk across time. Investing a fixed amount regularly, a habit called dollar-cost averaging, means you buy at different price levels rather than betting everything on one moment. It’s a quiet but powerful form of diversification.

    Understanding Correlation: The Secret Behind Diversification

    If you want to understand why diversification works, you need to know one word: correlation. It describes how closely two investments move together.

    When two assets are highly correlated, they rise and fall at the same time, so owning both adds little protection. When they have low or negative correlation, one can rise while the other falls, which balances your portfolio.

    Here’s the honest part: correlations aren’t fixed. In 2022, for example, stocks and bonds both declined in many markets at the same time, surprising investors who assumed bonds would always cushion stock losses. This doesn’t mean diversification failed. It means that no single mix works in every situation, which is exactly why spreading across several asset types, not just two, is so valuable.

    How to Build a Diversified Portfolio: Step by Step

    You don’t need to be a financial expert. Follow these steps.

    Step 1: Define Your Goals and Time Horizon

    Are you saving for a home in three years or retirement in thirty? Money you’ll need soon should be in safer assets. Money you won’t touch for decades can take more risk for more growth.

    Step 2: Know Your Risk Tolerance

    Ask yourself honestly: how would you feel if your portfolio dropped 20%? If that would keep you awake at night, you need a more conservative mix.

    Step 3: Choose Your Asset Allocation

    Asset allocation is how you divide your money among asset classes. A younger investor might choose a stock-heavy mix, while someone nearing retirement might favor more bonds and cash. The U.S. Securities and Exchange Commission explains this well in its guide to asset allocation and diversification on Investor.gov.

    Step 4: Use Funds to Spread Risk Cheaply

    Buying dozens of individual stocks is expensive and time-consuming. Instead, many people use:

    • Index funds, which track an entire market
    • Exchange-traded funds (ETFs), which trade like stocks but hold many assets inside
    • Target-date funds, which automatically adjust your mix as you approach a goal

    A single broad index fund can give you exposure to hundreds or even thousands of companies at once, making diversification affordable even with small amounts. For a deeper definition, Investopedia’s explanation of diversification is a useful reference.

    Step 5: Rebalance Regularly

    Over time, some investments grow faster than others and throw your mix off balance. If stocks surge, they may become a bigger share of your portfolio than you intended. Review your holdings once or twice a year and adjust back to your target. Rebalancing keeps your level of risk where you want it.

    [INTERNAL LINK: add a link here to your Growwxritik post on investing for beginners]

    Common Diversification Mistakes to Avoid

    Owning many similar investments. Ten tech stocks or five funds that hold the same companies is not real diversification.

    Over-diversifying. Holding too many investments makes your portfolio hard to track, adds fees, and can dilute your best ideas. Investors sometimes call this “diworsification.” For most people, a handful of broad funds is plenty.

    Ignoring costs. Some funds charge high fees that eat into returns. Compare expense ratios before you buy.

    Forgetting your emergency fund. True financial diversification starts with a cash safety net. Without one, you may be forced to sell investments at a loss when an emergency hits. [INTERNAL LINK: add a link here to your Growwxritik post on building an emergency fund]

    Chasing last year’s winner. Piling into whatever performed best recently often means buying high. A disciplined plan beats reacting to headlines.

    Neglecting your income sources. Diversification applies beyond investing. If your entire income depends on one employer or one client, adding a side income or a second skill is a form of diversification too.

    Does Diversification Guarantee Profits?

    No, and it’s important to be clear about that. Diversification does not guarantee a profit or protect against losses in a falling market. If the whole market drops, a diversified portfolio will usually drop too, though often by less than a concentrated one.

    What diversification does is manage risk. It improves your chances of steady, long-term growth while reducing the odds of a devastating loss. That’s a trade most long-term investors are happy to make.

    Frequently Asked Questions About Diversification

    How many investments do I need to be diversified?
    There’s no magic number, but research suggests that holding roughly 20 to 30 different stocks removes much of the risk tied to individual companies. Most people reach that level easily by owning one or two broad index funds.

    Can a beginner use diversification with a small amount of money?
    Yes. Low-cost index funds and ETFs let you own a slice of many companies for very little money, so you can start with a small amount and build gradually.

    Is diversification only for stocks?
    No. It applies to income sources, savings, property, and even currencies. Anywhere you could face a single point of failure, spreading your risk helps.

    How often should I review my diversified portfolio?
    Once or twice a year is enough for most people, or after a major life change such as a new job, marriage, or the birth of a child.

    Final Thoughts

    So, what is diversification, and why does it matter? It’s a simple, time-tested way of protecting your money from the unexpected. By spreading your investments across asset classes, industries, regions, and time, you avoid depending on any single outcome.

    You don’t need to be an expert or a high earner to benefit. Start by understanding your goals, choose a sensible mix, use low-cost funds, and rebalance occasionally. Over the years, diversification can be the difference between a portfolio that survives the storms and one that doesn’t.

    This article is for educational purposes only and isn’t financial advice. Consider speaking with a licensed financial professional about your own situation.