Category: Personal Finance & Budgeting

  • Needs vs Wants: The Essential 7-Step Guide to Smart Spending

    Needs vs Wants: The Essential 7-Step Guide to Smart Spending

    You get paid on Friday. By Wednesday, the money is gone, and you can’t fully explain where it went needs vs wants. Most of the time, the problem isn’t how much you earn. It’s confusion about needs vs wants.

    When every purchase feels urgent, everything starts to feel like a need. The data bundle, the new sneakers, the aso-ebi for the weekend party, the faster phone. Learning to separate needs vs wants is one of the most useful money skills you can build, and it costs nothing to learn.

    This guide gives you clear definitions, seven practical tests, real examples, and a simple budgeting system you can start using today.

    Needs vs Wants: What Is the Real Difference?

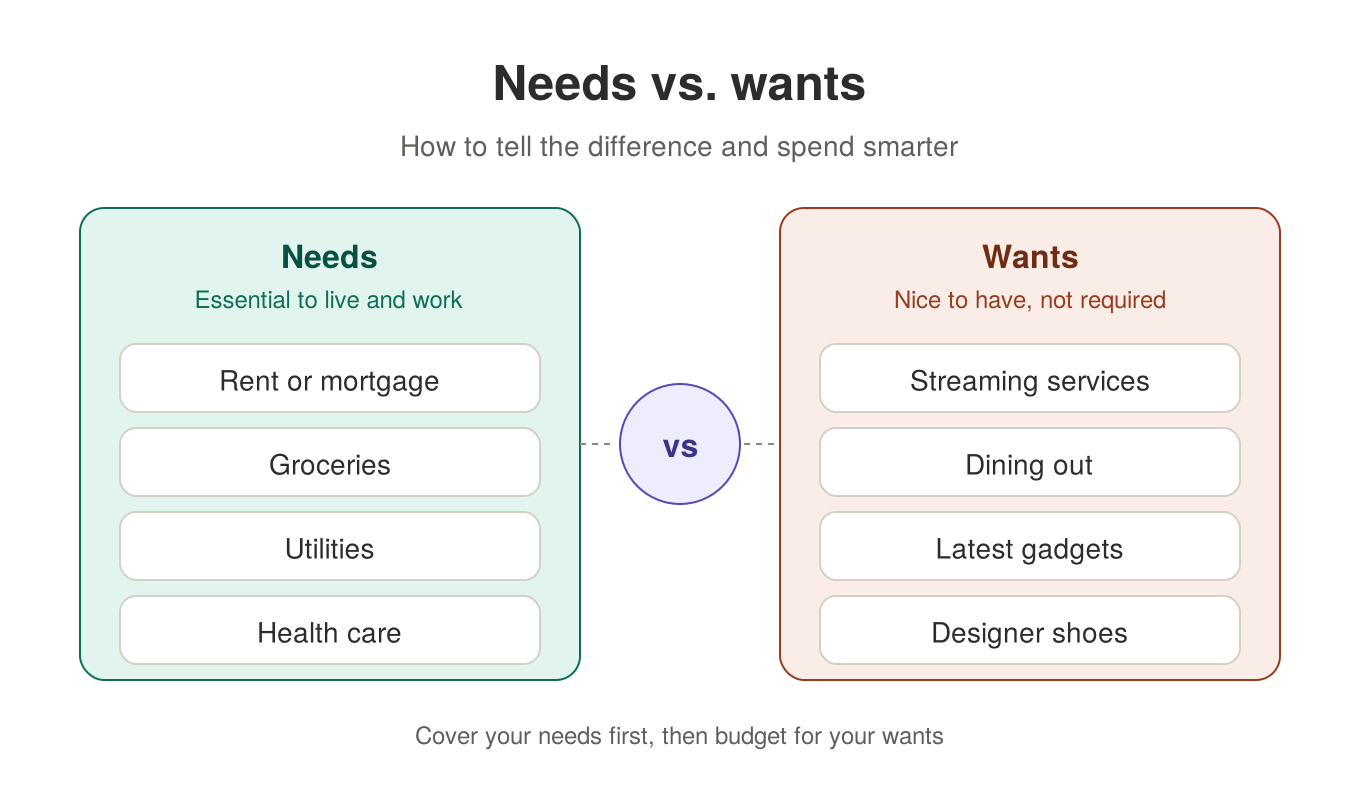
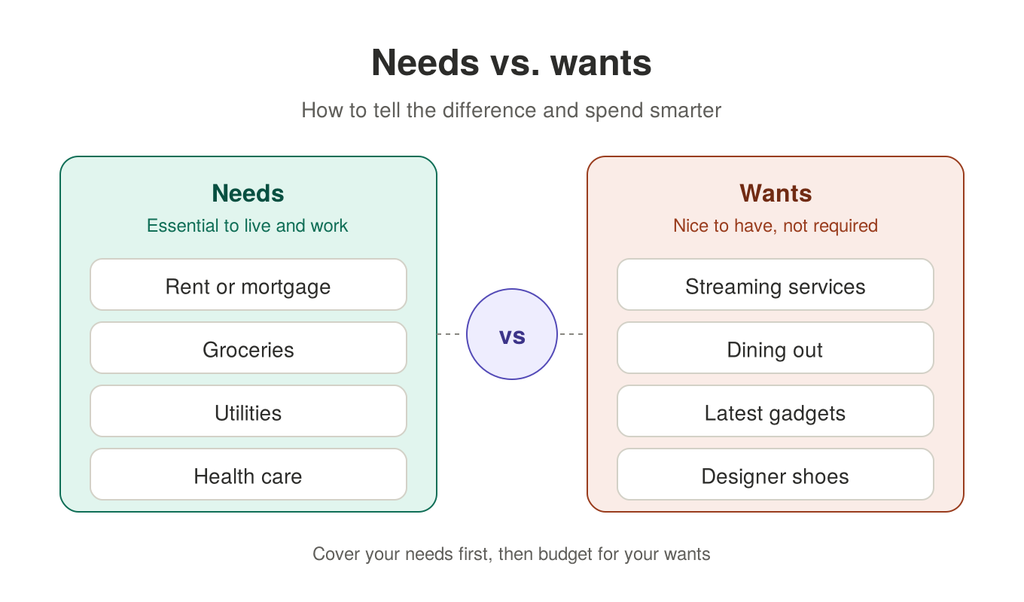
    A need is something you must have to stay safe, healthy, housed, fed, and able to earn a living. A want is anything that adds comfort, status, or enjoyment but that you could live without, at least for now.

    That sounds simple, yet real life blurs the line. A smartphone is a need if you freelance or run a small business online. Unlimited streaming data for football highlights all day? That’s probably a want.

    Here is a quick comparison:

    CategoryTypical NeedTypical Want
    FoodBasic groceries and home-cooked mealsDaily restaurant lunches and delivery fees
    HousingSafe, affordable rentUpgrading to a bigger flat for status
    TransportGetting to work or school reliablyRide-hailing every trip when a bus works
    CommunicationBasic airtime and dataPremium plans you barely use
    ClothingWork-appropriate, durable clothesDesigner labels and constant new outfits
    HealthMedicines, health cover, clinic visitsCosmetic extras and luxury wellness

    Notice the pattern. Most needs have a “want-sized” version attached to them. Food is a need. Eating out every day is the want version of that need.

    Why Confusing Needs vs Wants Quietly Drains Your Money

    Almost nobody wrecks their finances with one dramatic purchase. The damage comes from small, repeated spending that feels harmless in the moment.

    Say someone earns ₦300,000 a month and spends ₦3,000 a day on ride-hailing and snacks they call “essentials.” That’s roughly ₦90,000 a month, or 30 percent of their income. Yet the same person may struggle to save even ₦10,000.

    Getting needs vs wants right matters even more when prices climb. When inflation rises, essentials take a bigger share of your pay, so there is less room for mistakes. Borrowing costs and prices are shaped by decisions at the central bank, and our guide to central bank interest rates explains how that works in plain language.

    Credit makes the problem worse. Swiping a card or using a buy-now-pay-later app hides the pain of paying, so wants feel like needs. If you are unsure which tool suits you, our breakdown of credit cards vs debit cards will help.

    7 Simple Tests to Separate Needs vs Wants

    You don’t need all seven tests for every purchase. Pick the two or three that fit the moment.

    1. Ask the Survival Question

    Ask yourself: “Will my health, safety, housing, or income be at risk if I don’t buy this?” If the answer is yes, it’s a need. If the answer is “I’ll just feel a bit sad,” it’s a want.

    2. Try the “Skip It for 30 Days” Test

    Imagine going a month without the item. If life carries on normally, you’ve found a want. If something important breaks, such as your ability to get to work, it’s a need.

    3. Look for a Cheaper Version

    Real needs can usually be met in several ways. You need transport, but not necessarily a new car. You need a phone, but not necessarily the latest model. If a cheaper option solves the problem, the expensive upgrade is the want.

    4. Use the 48-Hour Rule

    For any non-essential purchase, wait two days before paying. Impulse fades fast. If you still want it after 48 hours and it fits your budget, buy it without guilt.

    5. Convert the Price Into Work Hours

    Divide the price by what you earn per hour. A ₦40,000 pair of shoes might equal a full week of effort for someone earning ₦1,000 an hour. Seen that way, many wants lose their shine.

    6. Check How Often You’ll Use It

    A needed item earns its place through repeated use. A treadmill used twice or a course never opened was never a need. Ask honestly, “How many times a month will this actually help me?”

    7. Ask Who You’re Buying It For

    Some of our biggest wants are really about impressing other people: the wedding outfit, the car, the party. There’s nothing wrong with enjoying life, but it helps to know whether you’re buying for yourself or for an audience.

    The Gray Area: When a Want Disguises Itself as a Need

    Honest needs vs wants decisions get tricky in the middle, where the same item can sit on both sides depending on your situation.

    A useful idea is to think in levels. The basic version of something is the need. Every upgrade above that level is a want.

    • Phone: A working phone is a need. A flagship model is a want.
    • Data: Enough to work, study, and stay in touch is a need. Heavy streaming plans are a want.
    • Transport: Reaching your workplace is a need. Choosing the most comfortable option every time is a want.
    • Housing: A safe, decent home is a need. Extra rooms and prestige addresses are wants.

    Context matters too. A laptop is a want for a casual browser, but it’s a need for a graphic designer. Your goals and your work decide where the line falls, so don’t borrow someone else’s definition.

    How to Build a Budget Around Needs vs Wants

    Once you’ve sorted needs vs wants on paper, a budget becomes much easier to follow. Here is a simple process:

    1. Write down your monthly income after tax. Use only money you can count on.
    2. List your fixed needs. Include rent, utilities, food, transport, school fees, and minimum debt payments.
    3. Set a ceiling for wants. Decide the amount in advance. Spending on wants isn’t the enemy. Unplanned spending on wants is.
    4. Pay yourself first. Move savings out the day you get paid, before the month’s temptations begin.
    5. Review weekly. A five-minute check keeps small leaks from becoming big ones.

    Many people use the 50/30/20 rule as a starting point: about half of income for needs, 30 percent for wants, and 20 percent for savings and debt repayment. Investopedia has a helpful explainer on the 50/30/20 budget rule if you want the full picture.

    Those percentages are a guide, not a law. If rent and food already take 70 percent of your pay, you’ll need to adjust. Our article on how to save money on a low income shows how to make progress even when the numbers are tight.

    If you struggle to stick to limits, try the cash method. Our guide to envelope budgeting shows how physical or digital envelopes make your “wants” limit hard to ignore. The Consumer Financial Protection Bureau also offers free budgeting tools and worksheets that anyone can use.

    Finally, give your savings a safe home. Keep them with a bank licensed by the Central Bank of Nigeria, and compare options in our guide to checking vs savings accounts.

    Pros and Cons of Prioritizing Needs vs Wants

    Like any money strategy, this one has strengths and limits.

    Pros

    • You see exactly where your money goes.
    • It reduces impulse buying and shopping regret.
    • It frees up money for savings and emergencies.
    • It builds a habit that works at any income level.

    Cons

    • Being too strict can make budgeting feel joyless.
    • The gray area takes honest self-reflection.
    • Family and social pressure can make “wants” feel compulsory.
    • It needs regular review as your income and life change.

    The fix for the cons is simple: budget a small, guilt-free amount for wants every month. A plan that includes fun is a plan you’ll actually keep.

    Common Needs vs Wants Mistakes to Avoid

    Even people with good intentions fall into these traps:

    • Labeling everything an “emergency.” If it wasn’t unexpected and necessary, it wasn’t one.
    • Ignoring small, repeated spending. Daily snacks, subscriptions, and transfer fees add up fast.
    • Treating debt payments as optional. Missed payments can damage your credit record. Our guide on how to build credit from scratch explains why consistent repayment matters.
    • Comparing yourself to others. Their income, debts, and priorities are not yours.
    • Skipping savings until “later.” Without a cushion, a single surprise bill turns a want into a loan.

    Frequently Asked Questions

    Is a phone a need or a want?

    It depends on how you use it. A basic working phone is a need for most people, especially if you work or study online. A premium model chosen for status or features you won’t use is a want.

    What is the 50/30/20 rule?

    It’s a budgeting guideline that splits after-tax income into 50 percent needs, 30 percent wants, and 20 percent savings and debt repayment. It’s a starting point, and you can adjust the numbers to match your cost of living.

    How do I stop impulse buying?

    Use the 48-hour rule, unsubscribe from promotional emails, and avoid saving card details on shopping apps. Writing items on a “wish list” instead of buying immediately also helps.

    Are savings a need or a want?

    Think of savings as a need. An emergency fund protects you when life goes wrong, so it belongs in your essentials, not your extras.

    How can I teach children the difference between needs vs wants?

    Use everyday examples. Let them pick between two things at the shop, explain why you can only afford one, and give them a small allowance to manage. Children learn needs vs wants fastest through real choices.

    What if my income is too low to have any wants?

    Even then, plan a very small amount for enjoyment, such as ₦2,000 a month. A tiny, planned treat keeps you motivated. It also stops you from breaking the whole budget in frustration.

    How often should I review my needs and wants list?

    Review it monthly, and again whenever your income, rent, or family situation changes. What counts as a need today may become a want next year, and the reverse is also true.

    Final Thoughts: Make Needs vs Wants a Habit

    Knowing the difference between needs vs wants won’t make you rich overnight. It will give you control, and control is where wealth starts. Every time you pause before a purchase and ask the right question, you move a little closer to your goals.

    Start small. Pick one test from this list and apply it to your next three purchases. Then write down your fixed needs, set a wants limit, and move something into savings the moment you’re paid.

    Want to keep going? Read our guide on envelope budgeting next, and explore more Growwxritik articles to build your money confidence one step at a time.

    Disclaimer: This article is for educational purposes only and is not personalized financial, legal, or investment advice. Consider speaking with a qualified professional before making major financial decisions.
  • How to Live on a Low Income and Still Save Money: 11 Smart Strategies That Work

    How to Live on a Low Income and Still Save Money: 11 Smart Strategies That Work

    If you’ve ever been told to “just save more,” you probably your income wanted to laugh. When rent, food, transport, and bills swallow almost every naira, dollar, or pound you earn, saving can feel like advice written for someone else.

    But here’s the truth: learning how to save money on a low income is not about earning like a millionaire. It’s about building small, repeatable habits that protect you from emergencies and slowly create breathing room. Even tiny amounts add up when they’re consistent.

    This guide shares 11 proven, realistic ways to live on a low income and still save money. No guilt, no unrealistic advice, just practical steps you can start this week.

    Why Saving Matters Even More on a Low Income

    When money is tight, a single surprise, such as a medical bill, a broken phone, or a few days of lost work, can force you into debt. Savings act as a buffer between you and that kind of crisis.

    You don’t need a large amount to feel the benefit. Studies of household finances consistently show that even a small emergency cushion reduces stress and the need to borrow at high interest. The goal isn’t to become wealthy overnight. It’s to get a little more secure every month.

    1. Know Exactly Where Your Money Goes

    You can’t fix what you can’t see. For one month, write down every expense, even small ones like snacks, data bundles, and transport fares. Use a notebook, a notes app, or a simple spreadsheet.

    Most people are surprised by what they find. Small daily purchases often add up to a surprisingly large monthly total. Once you can see the pattern, you can decide what’s worth keeping and what isn’t.

    2. Build a Simple, Realistic Budget

    A budget is just a plan for your money. On a low income, keep it simple. The 50/30/20 rule splits your income into needs, wants, and savings, but if your needs take up more than 50%, adjust it. Even a 70/25/5 split is a good start.

    If you want a hands-on method, try [INTERNAL LINK: add a link here to your Growwxritik post on envelope budgeting]. Giving every category a fixed amount makes overspending much harder.

    3. Pay Yourself First, Even if It’s Small

    Instead of saving whatever is left at the end of the month (which is often nothing), move a small amount into savings as soon as you get paid. Even 2% to 5% of your income is enough to begin.

    Treat it like a bill you owe to your future self. Saving a little consistently beats saving a lot occasionally.

    4. Start a Starter Emergency Fund

    Don’t wait until you can save three to six months of expenses. Start with a small target, such as one week of essentials, then build toward one month, and then more.

    Keep this money in a separate savings account, away from your daily spending money. If you’re unsure which type of account to use, [INTERNAL LINK: add a link here to your Growwxritik post on checking vs savings accounts] explains the differences.

    5. Cut Costs Where It Hurts Least

    You don’t have to give up everything you enjoy. Look for painless savings first:

    • Subscriptions: cancel streaming services, apps, or memberships you rarely use
    • Data and phone plans: compare providers and choose the plan that matches your real usage
    • Bank fees: switch to an account with low or no monthly charges
    • Impulse buys: wait 24 hours before buying anything non-essential

    Each small cut might only save a little, but together they can free up a meaningful monthly amount.

    6. Spend Smarter on Food

    Food is one of the biggest expenses for low-income households, and also one of the easiest places to save.

    Plan your meals. Decide what you’ll cook for the week before you shop.

    Write a list and stick to it. Shopping without a list is the fastest route to overspending.

    Buy staples in bulk. Rice, beans, flour, and oil are cheaper per unit in larger quantities, if you have storage space and can afford the upfront cost.

    Shop at local markets. Fresh produce is often cheaper than in supermarkets.

    Cook at home more often. Eating out regularly is one of the most common budget drains.

    Reduce food waste. Use leftovers and freeze extras.

    7. Lower Your Housing and Utility Costs

    Housing is usually the largest expense, so even small improvements make a difference. If you can, consider sharing accommodation, negotiating rent, or moving somewhere cheaper when your lease ends.

    You can also trim utilities. Switch off lights and unplug unused devices, use energy-efficient bulbs, and fix leaks quickly. For official tips on managing household costs, the Consumer Financial Protection Bureau’s budgeting resources are a trustworthy place to start.

    8. Avoid High-Interest Debt

    Debt is the biggest threat to anyone trying to save on a low income. High-interest loans and credit card balances can eat up your savings faster than you can build them.

    If you already have debt, pay the highest-interest balance first while making minimum payments on the rest. If you’re deciding whether to use cards at all, [INTERNAL LINK: add a link here to your Growwxritik post on credit cards vs debit cards] can help you choose wisely.

    9. Earn a Little Extra

    Cutting costs only goes so far. Increasing your income, even by a small amount, can speed up your progress dramatically.

    Realistic ways to earn more include:

    • Freelancing a skill such as writing, design, tutoring, or translation
    • Selling items you no longer use
    • Offering services in your community, like repairs, cleaning, or deliveries
    • Starting a small side business with low startup cost
    • Asking for a raise or applying for a better-paying role

    Put most of any extra income directly into savings so it doesn’t disappear into everyday spending.

    10. Use Free and Low-Cost Resources

    Many people overlook help that’s already available. Depending on where you live, look into:

    • Free or subsidized healthcare services
    • Community programs and food support
    • Free learning platforms for new skills
    • Public libraries for books, internet, and workshops
    • Student, senior, or low-income discounts

    Using what’s available isn’t a weakness. It’s smart money management.

    11. Save Windfalls and Celebrate Small Wins

    When you receive unexpected money, such as a bonus, a gift, or a tax refund, resist the urge to spend it all. Put at least half toward savings or debt.

    Also, celebrate your progress. Saving your first $10 or reaching your first week of emergency funds is a real achievement. Motivation matters, and small wins keep you going.

    Where Should You Keep Your Savings?

    Choose a safe, separate place for your savings so you’re less tempted to spend it. Options include a savings account, a fixed deposit, a cooperative savings group, or a reputable digital savings app, depending on where you live. Make sure any provider is licensed and that your deposits are protected by your country’s deposit insurance scheme where available.

    Avoid schemes that promise very high, fast returns. If it sounds too good to be true, it usually is, and low-income savers are often the target of scams. For more on how savings accounts work, Investopedia’s savings account guide is a helpful reference.

    Common Mistakes to Avoid

    Setting unrealistic goals. Saving 30% of a tight income will likely fail. Start small and increase gradually.

    Giving up after one bad month. Everyone slips sometimes. Restart the next day.

    Keeping savings in your spending account. Out of sight really does help.

    Comparing yourself to others. Your situation is your own. Focus on your progress.

    Ignoring small leaks. Daily small purchases quietly drain more than most people expect.

    Taking risks you can’t afford. Don’t put emergency savings into risky investments or unproven schemes.

    A Simple 30-Day Starter Plan

    If you’re not sure where to begin, try this:

    Week 1: Track every expense and list your income and bills.
    Week 2: Create a basic budget and cancel one unnecessary expense.
    Week 3: Open a separate savings account and set up an automatic transfer, even a small one.
    Week 4: Review your progress, adjust your budget, and plan one way to earn a little extra.

    By the end of the month, you’ll have a system in place and your first savings in the bank.

    Frequently Asked Questions

    How can I save money if I barely make enough to live on?
    Start by tracking your spending to find small leaks, then save a very small fixed amount each payday. Even 1% to 2% builds the habit, and you can increase it as you cut costs or earn more.

    How much should I save on a low income?
    There’s no fixed rule. Many experts suggest 10% to 20%, but on a tight income, 2% to 5% is a perfectly good start. Consistency matters more than the amount.

    What is the best way to start an emergency fund with little money?
    Set a tiny first goal, like one week of essential expenses. Save in a separate account and add small amounts regularly until you reach one month, then keep building.

    Should I pay off debt or save first?
    Do both in order: build a small starter emergency fund first so you’re not forced to borrow again, then focus on high-interest debt while still saving a little.

    Is it possible to build wealth on a low income?
    Yes, though it takes time. Combining steady saving, avoiding high-interest debt, growing your skills, and increasing your income gradually can lead to real financial progress.

    Final Thoughts

    Learning how to save money on a low income is less about having more and more about managing what you have with intention. Track your spending, build a simple budget, pay yourself first, cut painless costs, avoid expensive debt, and look for ways to earn a little extra.

    Progress may feel slow at first, and that’s normal. But every small amount you save is a step toward security, confidence, and choices. Start with one habit this week. Then add another. Over time, those small steps can change your financial life.

    This article is for educational purposes only and isn’t financial advice. Financial products, protections, and programs vary by country, so check with your provider or a licensed professional.

  • Envelope Budgeting: How the Cash Envelope System Works

    Envelope Budgeting: How the Cash Envelope System Works

    Most people don’t overspend because they’re careless. They overspend because money has become invisible. You tap a card, scan a phone, click “buy now,” and the cost barely registers until the statement arrives. By then, it’s too late to do anything about it.

    Envelope budgeting fixes that problem in one of the oldest ways possible: you put physical cash into labeled envelopes, and when an envelope is empty, that category is done for the month.

    It sounds almost too simple to work. Yet this method has helped families, students, freelancers, and first-time budgeters get control of their spending for generations. In this guide, you’ll learn exactly how the cash envelope system works, how to set it up step by step, what to do when things go wrong, and how to adapt it to a world where so much of our money is digital.

    What Is Envelope Budgeting?

    Envelope budgeting, also called the cash envelope system, is a budgeting method where you divide your spending money into categories and assign a physical envelope to each one. Groceries get an envelope. Transport gets an envelope. Eating out, entertainment, and personal spending each get their own.

    At the start of the month (or each pay period), you withdraw the cash you plan to spend and distribute it among the envelopes. Whenever you spend in a category, you pay from that envelope. When the money runs out, you stop spending in that category until the next cycle.

    That’s the whole system. The power is in its simplicity: your budget stops being a number on a spreadsheet and becomes something you can see and hold.

    Why the Cash Envelope System Works

    The method works because of how our brains treat money. Research in behavioral finance has repeatedly shown that people feel the “pain of paying” more when they hand over physical cash than when they swipe a card. Spending cash feels like losing something real, so you naturally think twice.

    Here are the main reasons envelope budgeting is effective:

    It creates a hard spending limit. A budget on paper is a suggestion. An empty envelope is a boundary. You can’t overspend what you don’t have in your hand.

    It makes tradeoffs visible. If your entertainment envelope has $20 left and there are two weeks to go, you have to decide what matters. That kind of decision-making builds financial awareness.

    It’s easy to understand. You don’t need budgeting software, financial vocabulary, or a spreadsheet. Anyone in the household, including teenagers, can follow it.

    It reduces impulse buying. When you have to open an envelope and count out bills, the quick, thoughtless purchase becomes a little harder to justify.

    What You’ll Need to Get Started

    You don’t need much:

    • A set of envelopes (plain paper envelopes work fine, or buy a dedicated cash envelope wallet)
    • A pen or marker for labeling
    • Your monthly income and a list of expenses
    • Cash withdrawn from your bank account
    • A safe place to keep your envelopes

    How to Set Up Envelope Budgeting: Step by Step

    Step 1: Calculate Your Monthly Income

    Start with how much money you actually take home each month, after taxes and deductions. If your income is irregular, as it is for many freelancers and business owners, use your lowest-earning month from the past six months as your baseline. This keeps the budget realistic.

    Step 2: List Your Expenses and Sort Them

    Write down everything you spend money on. Then split the list into two groups:

    Fixed expenses stay the same every month, like rent, loan payments, insurance, and subscriptions. These are usually paid by bank transfer or direct debit, so they don’t need envelopes.

    Variable expenses change from month to month, like groceries, fuel, dining out, clothing, entertainment, and personal care. These are the categories that belong in your envelopes, because they’re where most overspending happens.

    Step 3: Choose Your Envelope Categories

    Pick the variable categories where you most need control. Common choices include:

    • Groceries
    • Transport or fuel
    • Eating out
    • Entertainment
    • Clothing and shopping
    • Personal care
    • Household supplies
    • Miscellaneous or “fun money”

    Start with five to eight envelopes. Too many becomes tedious, and too few doesn’t give you enough control.

    Step 4: Set a Budget for Each Envelope

    Look at your past two or three months of spending to estimate realistic amounts. If you’ve been spending $400 a month on groceries, don’t suddenly assign $150 and expect it to work. Start with honest numbers, then trim gradually.

    Make sure your total envelope amounts, plus your fixed expenses and savings, don’t exceed your income. If they do, you’ll need to reduce something.

    Step 5: Withdraw the Cash and Fill the Envelopes

    Take out the total amount you need from your bank account, ideally in smaller denominations so it’s easier to divide. Write the category and amount on each envelope, then place the cash inside.

    Step 6: Spend Only From the Envelope

    When you shop, take only the relevant envelope with you. Going to the grocery store? Take the grocery envelope and leave the rest at home. This habit alone prevents a lot of accidental overspending.

    Step 7: Track and Adjust

    Keep the receipts, or jot down what you spent inside each envelope. At the end of the month, review what happened. Which envelopes ran out early? Which had money left over? Use that information to adjust the amounts for next month.

    A Simple Example

    Say you earn $2,000 a month after tax. Your rent, utilities, and phone bill come to $1,100, and you want to save $200. That leaves $700 for variable spending, which you divide like this:

    EnvelopeMonthly Amount
    Groceries$300
    Transport$120
    Eating out$80
    Entertainment$60
    Personal care$40
    Miscellaneous$100
    Total$700

    Your fixed bills and savings are handled by bank transfer, and the $700 sits in your envelopes. If the eating-out envelope is empty by the 20th, you cook at home until payday. No guilt, no debt, no surprise.

    What Happens When an Envelope Runs Out?

    This is the question every beginner asks, and it’s where the system earns its value. You have a few options:

    Stop spending in that category. This is the purest version of the method, and it teaches discipline fast.

    Borrow from another envelope. If you must, move money from a category with a surplus, such as entertainment, to cover a real need. Treat this as an exception, not a habit.

    Adjust next month’s budget. If you consistently run out of money in one envelope, your original estimate was too low. Increase it and lower something else.

    The point isn’t punishment. It’s information. An empty envelope tells you something real about your spending.

    What to Do With Leftover Money

    Money left in an envelope at month’s end is a win. You can handle it in one of three ways:

    • Roll it over to the same envelope for next month
    • Move it into your savings or emergency fund
    • Put it toward debt repayment

    Many people find that moving leftovers into savings is the most motivating choice, since it turns good spending habits into visible progress.

    Pros and Cons of the Cash Envelope System

    Advantages

    • Easy to set up and easy to understand
    • Builds awareness of where your money goes
    • Naturally limits overspending
    • Works without technology or fees
    • Helps people get out of credit card debt

    Disadvantages

    • Carrying cash carries a risk of loss or theft
    • Many bills and online purchases can’t be paid in cash
    • It requires a trip to the bank or ATM
    • Tracking can feel inconvenient compared to automated apps
    • You may miss out on card rewards or cashback

    None of these are dealbreakers, but they’re worth knowing about before you start.

    Can You Do Envelope Budgeting Digitally?

    Yes. Because cash isn’t practical for everyone, digital versions have become popular. Budgeting apps let you create “virtual envelopes” and assign money to each category, so you can see your remaining balance as you spend with a card. Some banks also let you create separate sub-accounts or “pots” for different spending goals.

    Digital envelopes give you the same structure with more convenience and better record-keeping. The tradeoff is that they lose some of the psychological bite of handing over real bills. A good approach is a hybrid: use physical cash for the categories where you struggle most, such as eating out and shopping, and digital envelopes for everything else.

    Tips for Making Envelope Budgeting Work

    Be realistic from the start. An overly strict budget will fail by week two. Give yourself some breathing room.

    Include a “fun money” envelope. Budgets that leave no room for enjoyment don’t last. A small amount for guilt-free spending keeps you motivated.

    Keep your envelopes secure. Don’t carry more cash than you need, and store the rest somewhere safe at home.

    Involve your household. If you share finances with a partner or family, agree on the categories and amounts together so everyone follows the same plan.

    Review monthly. Your life changes, and your budget should change with it.

    Start small. If a full system feels like too much, begin with just the one or two categories where you overspend most.

    Common Mistakes to Avoid

    The biggest mistake is making the budget too tight, then giving up when it fails. Another is forgetting irregular expenses, such as car repairs, gifts, or school fees. Consider creating a small “sinking fund” envelope for these so they don’t wreck your month.

    Also avoid dipping into your savings envelope for non-emergencies, and don’t treat the system as a punishment. It’s a tool to give you control, not a test you can fail.

    Is Envelope Budgeting Right for You?

    The cash envelope system is especially useful if you tend to overspend on cards, you’re paying off debt, you’re new to budgeting, or you simply want a clear picture of your spending. It may be less suitable if most of your spending happens online or if carrying cash isn’t safe where you live. In that case, the digital approach is the better fit.

    Final Thoughts

    Envelope budgeting has lasted for decades for a simple reason: it works with human psychology instead of against it. When your money is limited to what’s in front of you, you make better choices without needing willpower or complicated tools.

    You don’t have to be perfect. Start with a few categories, fill your envelopes this month, and see what you learn. Within a few weeks, you’ll likely notice that you’re spending more intentionally and worrying less about money.

    Ready to try it? Grab a few envelopes, work out your numbers, and give the cash envelope system one full month. Your future self will thank you.